Kingman, AZ USDA Loans: Zero Down Is Possible!
Kingman is a Route 66 town with real deals and a map full of zero-down USDA neighborhoods. Here is the income catch, the payment math on a real Kingman price, and how to check any address yourself -- from a broker who has actually been to the museum.
Kingman, AZ USDA Loans: Zero Down Is Possible!
When I sat down to write this, Zillow showed about 1,300 homes for sale in Kingman. And a big share of them sit in neighborhoods that qualify for a zero-down USDA loan.
Not "low down payment." Not a typo. Zero.
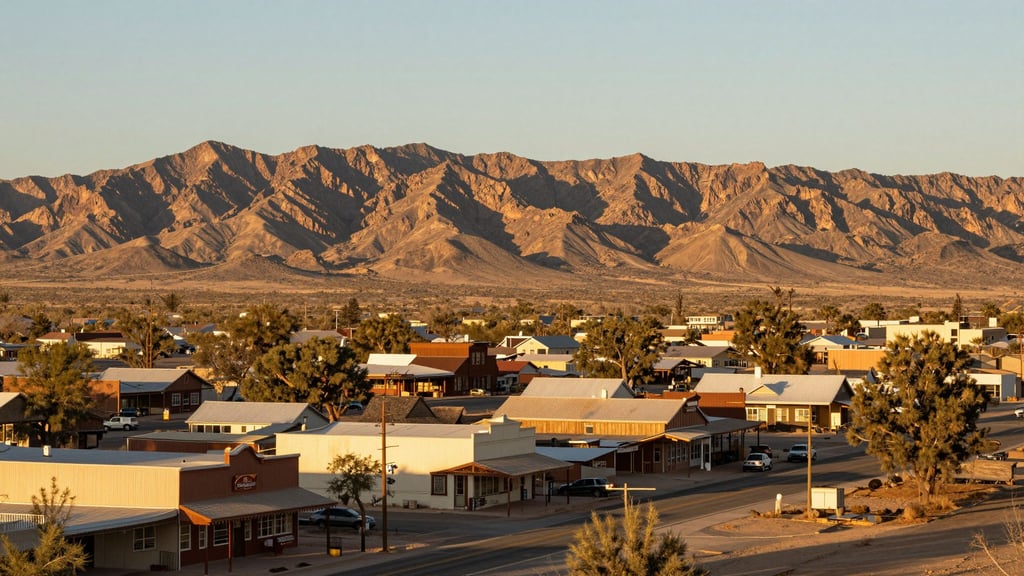
I remember the first time I visited Kingman. My wife loves nostalgia and museums, so we ended up at the Arizona Route 66 museum -- which, I admit, is a lot more interesting than I thought it would be. The reason I was excited to go is that Kingman is known for having some pretty great deals when it comes to real estate. It's also far enough outside of Phoenix -- about 185 miles -- that it would easily qualify as a second home for residents of Maricopa County.
But that's not what I'm here to talk about. Today I want to tell you how you can buy a home in Kingman with absolutely zero down.
Pull up a chair and let me tell you about USDA loans, partner!
So what is a USDA loan, anyway?
USDA loans are backed by the United States Department of Agriculture, and they exist to help people buy homes in smaller towns. The program's own guaranteed loan page leads with 100% financing, which is government-speak for: you can finance the whole price of the house and bring zero dollars to the down payment.
Here's the part that surprises people about Kingman specifically. USDA loans are meant for rural areas, and Mohave County is officially a metro county (the feds count it in the Lake Havasu City–Kingman metro area). But the eligibility map doesn't care about labels -- it cares about addresses. And when you check addresses in Kingman, address after address comes back eligible.
A metro-county city where most of the map still screens eligible for zero down. That's the whole weird trick.
The catch: income limits
There's always a catch, so here's this one: USDA loans have a household income cap. The program is designed for folks of modest-to-middle incomes, so you have to fit under the ceiling.
For the Kingman area, the most recently published table (stamped July 13, 2026 -- USDA adjusts these numbers every year) puts the guaranteed-loan limit at $122,800 for a household of one to four people, and $162,100 for five to eight. And honestly? For a town where the median sale price this fall was around $279,000 (that's Redfin's number), a $122,800 income ceiling is generous. Most Kingman buyers I can think of fit under it.
One more fine-print thing: those limits are published for the Lake Havasu City–Kingman metro area, not for "Mohave County" -- the table doesn't have a Mohave County line. Same numbers either way, but now you know why the geography reads funny.
What zero down does to the math
Let's use the median-priced Kingman house as our example -- call it $279,000, because that's what Redfin says sellers there have actually been getting this fall.
Twenty percent down on that house would be $55,800.
Zero down is $0.
So what does the payment look like? Let me run some quick math for you. Say the rate is 6.5% -- I picked that as a round number for the math; your real quote will move around -- on $279,000 financed for 30 years. The principal and interest comes to about $1,763 a month.
Now the honest fine print: your real payment adds property taxes, homeowner's insurance, and USDA's own fees (an upfront fee you can finance into the loan, plus a small annual one). So treat my $1,763 as the shape of the math, not a quote. The real number I'd give you on the phone will run a little higher -- but nowhere near "save up $55,800 first" higher.
And here's a nice bonus baked into the regulation: the seller can contribute up to 6% of the price toward your closing costs and prepaid items. On a $279,000 house that's up to $16,740 of help with the parts of buying that aren't the down payment.
Run your address through the map
So how do you know if the house you like qualifies? You check the address. That's genuinely the whole process:
- Find the house (or the neighborhood) you like in Kingman.
- Plug the address into USDA's eligibility site.
- Read the answer: eligible, not eligible, or "unable to determine" -- in which case you ask me, and I run it down with the lender.
I did some checking around Kingman myself for this article. Downtown, the courthouse area, the Stockton Hill Road corridor, out toward the hospital -- every address I sampled came back eligible. Two honest disclosures, because I'd rather you hear them from me: all my sample points were in the central and northern parts of town, and a few spots in south Kingman don't return a clear answer on the public map -- not "no," just "go check this one properly." Your exact address gets checked exactly.
And the map is the screening tool, not the final word. The lender makes the final eligibility call on the specific property, so nobody should buy (or skip) a house off the map alone.
Can you use it for a second home?
Remember how I said Kingman is far enough from Phoenix to make a great second home? Here's where I pump the brakes.
USDA loans are for the home you live in. The rules require you to occupy the property as your primary residence (60-day rule -- it's literally in the regulation). A USDA loan won't finance the Kingman house you visit on weekends.
The second home is a story for another day -- and another loan type. What USDA will do is take a Phoenix renter and make them a Kingman homeowner for zero down. Which, if you think about the math we just did, is kind of a big deal.
Questions I get about buying in Kingman with USDA
Is it really zero down? Or is there a catch? It's really zero down -- "100% financing" is the program's own language. The catches are the ones we covered: the income cap and the property address. If you fit under both, the down payment is genuinely $0.
What's the income cap for Kingman again? $122,800 for a household of one to four, $162,100 for five to eight, per the published table for the Lake Havasu City–Kingman area (stamped July 13, 2026; USDA adjusts annually). Household income counts everyone who'll live in the house, not just the borrowers.
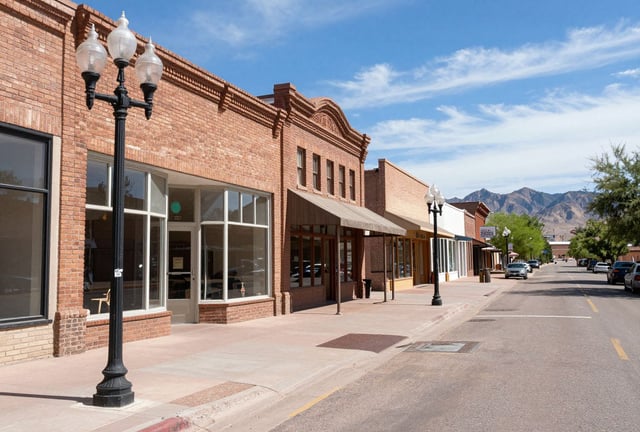
Does the house have to be out in the sticks? Nope -- and Kingman is proof. The map decides, street by street. The chamber of commerce calls Kingman "The Heart of Historic Route 66," and the heart of Route 66 screens eligible for zero-down financing all over town. You're buying in an honest-to-goodness city with hospitals, museums, and an I-40 on-ramp -- not homesteading.
If you want the real number on a real house
Go find an address in Kingman you like. Run it through the map. Then call me at (480) 613-8040 and I'll turn the round-number math into a real quote on that real house -- and tell you exactly what it costs to get to the closing table with zero down.
You bring the address. I'll bring the numbers. And if you get out to the Route 66 museum while you're house hunting, take your time -- it's better than it looks from the parking lot.
Related Topics
Michael George
NMLS #2280851I'm an Arizona mortgage broker and I've helped buyers and homeowners across the state since 2001. I work with FHA, VA, Conventional, Jumbo, and USDA loans, plus refinancing — explaining every option in plain English so you can make the right call with confidence.
View more articles by this authorWhat Our Clients Say
Join thousands of happy homeowners who trusted us with their mortgage journey
Leon Bucci
FHA Loan"We are first time homebuyers, and we needed an FHA loan. We were pre-qualified for a great interest rate with only 3% down. We were so nervous, but our mortgage broker made us aware of all the pros and cons of several different mortgage programs. Call the Mortgage Genius-- 10/10!"
Michele Dutily
Refinance"Having a hard time finding the words to express how amazing my experience with Michael was. I will, however, refer anyone I know that is looking to purchase or refinance a home to Michael."
Judy Baeza
Multiple Loans"I had Michael George as my Mortgage Broker on two home loans & never worked with anyone so honest, helpful & competitively priced compared to other brokers I used."