Can You Get a USDA Loan in Safford, Arizona? What the Map Shows
Search "USDA loan Safford" and you get loan-officer template pages with Alabama phone numbers. So I went to USDA's actual map data for the Gila Valley. Here is what it shows, and how to check your own address.
Can You Get a USDA Loan in Safford, Arizona? What the Map Shows
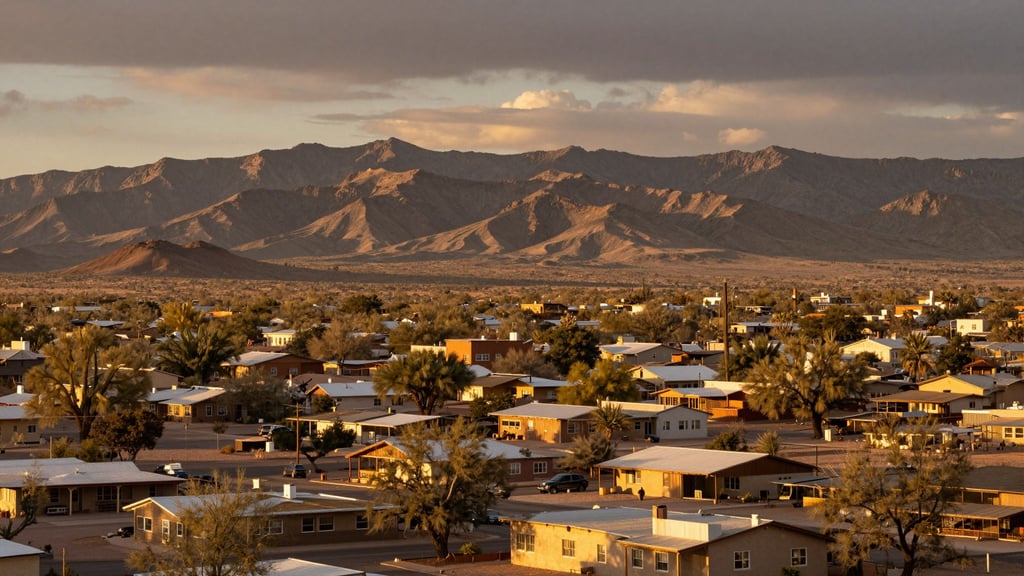
Safford is the biggest town in Arizona's Gila Valley: about 10,000 people, a county seat, a hospital, and Mount Graham watching over all of it. It is also exactly the kind of place the USDA loan program was drawn for. So when I went looking for a straight answer to the question in the title, I figured someone had written it down.
Nobody had. I searched the way a Safford homebuyer would, and the results were a junk drawer: the same "USDA Loans | Affordable Rural Home Financing" template page copy-pasted across a pile of loan officers' sites (most with Alabama, Louisiana, or Utah phone numbers), an Instagram Reel about a county in California, a MapQuest listing, and one news article about USDA programs in the Northern Mariana Islands. Not one page about Safford.
So I did the homework against the government's own data instead. Here is what it shows.
Is Safford, Arizona Eligible for USDA Loans?
The short answer: central Safford screens as eligible. USDA publishes an eligibility map for its Single Family Housing programs, and I checked five spots across town against that map's underlying data on October 21, 2026. All five came back "Eligible." Downtown, the neighborhoods along Highway 191, the west side -- the heart of Safford sits inside a USDA-eligible rural area.
Two honest footnotes before you run to Zillow. First, USDA makes you accept a disclaimer before the map even opens, and it is worth reading: "Final determination of property eligibility must be made by Rural Development upon receipt of a complete application." The map is a screen, and your lender's submission gets the final word. Second, the map works block by block, not county by county. Graham County is officially rural (the Census Bureau's urban-rural coding puts it in the nonmetro column), but that does not make every address in it eligible. The specific house decides.
USDA Income Limits for Graham County (FY 2026)
The property is half the test. The other half is your household's adjusted income, which has to fit under the limit for the county where the home sits. USDA publishes those limits by fiscal year, and the ones below are current for fiscal year 2026 (USDA issued them July 13, 2026):
- Guaranteed program, 1 to 4 people: $122,800
- Guaranteed program, 5 to 8 people: $162,100
That first number catches people off guard. A family of four in Graham County can earn six figures and still qualify, because "adjusted income" counts everyone who will live in the home and the lender documents it the way USDA's rules require (7 CFR 3555.151(a)).
USDA also runs a separate direct loan program with lower income tiers (very low and low income, published in the same county tables). It is a different lane with its own process; the link to USDA's direct-loan table is in the checklist below.
One more thing about those numbers: they reset every October 1 with the federal fiscal year. I explained why that trips up so many articles in our post on USDA loan fees and the fiscal-year reset. If a website quotes income limits with no date attached, that is your clue to keep scrolling.
How a USDA Loan Works in Safford
The guaranteed program's headline is the one everybody knows: no down payment. USDA's program page describes eligible buyers purchasing "with 100% financing," and that is the design -- the buyer brings little to no cash of their own, and USDA's guarantee is what makes a lender comfortable offering it. The upfront guarantee fee can be financed into the loan, and a seller is allowed to contribute up to 6 percent of the sales price toward your closing costs (7 CFR 3555.102(h)), so the cash-to-close math can stay small.
The shape of the loan is simple by regulation: a fixed rate, a term capped at 30 years, and no adjustable-rate mortgages, balloon notes, or prepayment penalties (7 CFR 3555.104). What you sign in Safford is what you pay for the next three decades, and there is no penalty for paying it off early.
What Kind of Home Qualifies in Safford?
The program has a personality: it exists to put regular people into modest homes, and the rules say so. The dwelling must be "modest, decent, safe, and sanitary" (7 CFR 3555.151(d)), and USDA defines modest as housing a low- or moderate-income borrower can afford. New construction and existing homes both qualify.
It is also a homeownership program, in the letter of the rules: you agree to occupy the home as your primary residence, and the handbook requires you to actually move in within 60 days of closing. Investment properties do not qualify. Manufactured homes can qualify too, but under their own stricter rulebook (new units, permanent foundation), so ask before you fall in love with a listing.
How to Check Your Own Safford Address
Five minutes, no account needed:
- Go to USDA's eligibility site and pick the Single Family Housing Guaranteed loan program.
- Accept the disclaimer, then type a specific address -- the tool takes addresses one at a time.
- Read the answer. The handbook says the tool returns one of three outcomes: Eligible, Ineligible, or Unable to Determine.
If your address comes back Eligible, the screen has done its job; the lender confirms it with Rural Development during the application. That is the order of operations: map first for hope, application for truth.
Why Is Nobody Else Writing About This?
Honestly? Because Safford is small, and national content farms write for big-search-volume cities. The same template page ranks in ten states because someone typed it once and pointed it at every town with a zip code. Small towns do not move the needle for those sites. They move the needle for the people who live in them -- and around 40,000 of those people live in Graham County, a chunk of them trying to buy their first house with as little cash as possible.
That is who this one is for. You deserve better than a template with an Alabama phone number on it.
Where to Check It Yourself
- USDA property eligibility site (the map and the address lookup)
- Guaranteed program income limits, FY 2026 (PDF)
- Direct loan income limits, FY 2026 (PDF)
- The rules themselves, 7 CFR 3555 (eCFR)
- USDA's guaranteed loan program page
If You Are House Hunting in Safford
Our full walkthrough of the USDA home purchase loan covers the whole program -- eligibility, the map, income math, and how we run these loans for buyers across rural Arizona. If you are weighing every option, our guide to zero down mortgages in Arizona compares USDA against VA and down-payment assistance side by side.
And if you want a human who has actually pulled up the Safford map, call me at (480) 613-8040. I keep the county tables current, and I answer my own phone.
Related Topics
Michael George
NMLS #2280851I'm an Arizona mortgage broker and I've helped buyers and homeowners across the state since 2001. I work with FHA, VA, Conventional, Jumbo, and USDA loans, plus refinancing — explaining every option in plain English so you can make the right call with confidence.
View more articles by this authorWhat Our Clients Say
Join thousands of happy homeowners who trusted us with their mortgage journey
Leon Bucci
FHA Loan"We are first time homebuyers, and we needed an FHA loan. We were pre-qualified for a great interest rate with only 3% down. We were so nervous, but our mortgage broker made us aware of all the pros and cons of several different mortgage programs. Call the Mortgage Genius-- 10/10!"
Michele Dutily
Refinance"Having a hard time finding the words to express how amazing my experience with Michael was. I will, however, refer anyone I know that is looking to purchase or refinance a home to Michael."
Judy Baeza
Multiple Loans"I had Michael George as my Mortgage Broker on two home loans & never worked with anyone so honest, helpful & competitively priced compared to other brokers I used."